Scaling a Rental Arbitrage Portfolio Beyond One Unit
Diversifying across units solves cash-flow risk but multiplies fixed lease obligations.
A single rental arbitrage unit is a fragile business, and the math behind it breaks down fast under any kind of stress. The structure is familiar to most operators already: sign a long-term lease, furnish the unit, then earn the spread between nightly revenue and monthly rent. No mortgage, no equity, but also no buffer. Rent is due on the 1st whether the unit books three nights that month or twenty. That fixed obligation is what makes the model affordable to enter and dangerous to run on one unit alone, because a single slow month has nothing to hide behind.
The cost side compounds the exposure. Airbnb takes about 15.5% of gross revenue off the top as a host service fee, before you see a dollar. So a unit that was penciled out on optimistic early projections often needs meaningfully more nightly revenue than expected just to clear break-even. Add cleaning, utilities, and furnishing costs that depreciate the moment they're installed: the capital you put into one unit builds nothing that holds value. A platform policy shift, a new local ordinance, or a run of bad reviews hits that one revenue stream directly, with no second unit to absorb the loss. That single point of failure is the exact problem scaling to multiple units is meant to solve.
What the step to multiple units fixes (and what it doesn't)
Adding units diversifies revenue across different booking windows, so a slow week in one market or one building doesn't sink the whole operation. A strong-performing unit can carry a weaker one for a stretch. Overhead also stops growing in lockstep with unit count once basic systems are running, because the same cleaner, pricing tool, and booking workflow can cover more doors at no added cost. There's also a capital velocity advantage specific to arbitrage: profits generated monthly can go straight into securing the next lease, which compresses the timeline to a multi-unit portfolio far faster than equity-dependent ownership models allow.
Scale fixes revenue concentration risk, but it also multiplies how much fixed cost you're exposed to. Each new lease is another monthly obligation you can't negotiate away, and a bad winter or a sudden regulatory change hits every lease at once, not just one. None of those obligations sit on a hard asset. The property-ownership camp raises a structural objection: arbitrage capital can lose most of its value quickly if a unit sits vacant, and a landlord can end the arrangement without much notice. Both points are accurate. The arbitrage model is built for cash-flow return and capital that moves fast, not for accumulating equity, and an operator who scales with that trade-off in mind can plan around it.
Unit economics that hold at scale: the revenue threshold and cost benchmarks that matter now
The revenue assumptions that worked for arbitrage operators in 2022 don't hold anymore. Margins have tightened, and an operator scaling today needs sharper benchmarks, not the rough math that got the first unit off the ground. The core calculation hasn't changed in form: gross nightly revenue minus fixed monthly rent sets the arbitrage premium, and whatever survives platform fees, cleaning costs, utilities, and other operating expenses is actual profit. What's changed is how much slack that calculation has left in it.
Before you sign a lease on any prospective unit, you need to run its break-even occupancy. Using a sample monthly rent, nightly rate, and set of monthly expenses, break-even is near 48.2% occupancy, a threshold that has to be checked against local comps. Build in the recurring costs that quietly compress margin: cleaning per turnover, consumables restocked every month, property management software, and insurance. None of those are optional line items, and skipping any of them in a projection is how a unit that looks profitable on paper turns out not to be. Before adding any new unit, keep at least three months of that unit's rent in reserve. That reserve is the only real protection against a slow season or a sudden platform disruption, and it should be treated as non-negotiable.
The broader market context matters here too. In 2025, short-term rental demand grew faster than hotel demand, which actually contracted slightly that year, but supply is projected to grow significantly in 2026. When more supply chases the same guest pool, occupancy volume alone won't protect margins the way it used to. Pricing strategy and unit quality carry more of the weight now, and any operator running these numbers should treat them as a framework to adapt to a specific market, not a formula guaranteed to repeat.
Market and regulatory selection as the first decision in any expansion
Before a second lease gets signed, market selection needs to be treated as a legal question, not just a revenue question. In a growing number of cities, the regulatory environment decides whether the business is viable there, independent of how good the numbers look. Regulatory exposure can invalidate an entire portfolio overnight. The legal map determines which markets are viable before the projected spread even factors in.
That map has split into two distinct tracks. Some jurisdictions are handing enforcement agencies stronger tools to crack down on short-term rentals. Others are pulling that authority back from cities entirely through state preemption. If you're building a portfolio rather than running one unit, those two tracks leave you with very different risk profiles. On the restrictive end, NYC, San Francisco, and Los Angeles block traditional whole-home arbitrage with primary-residence requirements. NYC goes further and requires host presence during every stay, so even a primary resident's whole-home rental is illegal under the ordinance. Seattle caps operators at two units, with at least one required to be the operator's primary residence. You wouldn't want to build a multi-unit arbitrage strategy around any of these markets.
Preemption states sit on the other end, and they're the markets where portfolios can be built with some durability. State preemption stops most individual cities from banning short-term rentals outright, leaving local governments to regulate narrower things: health and safety, taxes, nuisance complaints, licensing, parking, occupancy limits. Arizona is the clearest example of a fully preemptive state. Florida offers partial preemption, grandfathering in local bans that predate 2011 but preventing new ones. Idaho and Indiana both joined the preemption column in 2026. Idaho's law, effective July 1, 2026, specifically blocks cities from imposing owner-occupancy requirements, caps on the number or density of short-term rentals (including spacing rules and rental-day limits), or STR-specific licensing schemes.
Smaller and mid-sized cities deserve more attention than they typically get in this conversation. Major metros draw the regulatory headlines, but plenty of second-tier cities have quietly advanced their own ordinances, including citywide permit caps and separation requirements between short-term rental properties. If you scale into smaller markets, you need to check those rules with the same rigor you'd apply to a major city. Before committing to any new market, run through the same checklist every time: state preemption status, city permit requirements and caps, primary-residence rules, tax obligations, and any HOA restrictions that apply. Preemption status is the single clearest signal of whether a market will still allow this business to operate in two years, and it belongs at the top of that checklist, not somewhere further down.
Building a landlord pipeline: treating property acquisition as a repeatable sales process
Once a market clears the regulatory and economic checks, the actual constraint on growth becomes landlord acquisition. In functioning 2026 markets, closing one signed lease takes a meaningful number of pitches, and a single week of focused outreach at scale typically produces only a handful of real conversations and fewer signed agreements than that. Operators who expect a faster ratio tend to stall out after their first unit, mistaking one early yes for a repeatable process rather than treating acquisition as a funnel that needs constant volume feeding into it.
The pitch that works now leads with control and protection over rent economics. A landlord hearing about arbitrage for the first time doesn't need to be sold on upside, they need to be shown that the arrangement reduces their risk compared to a standard tenant. That means you offer guaranteed rent paid on the 1st whether or not the operator's unit is occupied that month, insurance coverage that names the landlord directly, professional cleaning after every guest stay, and monthly condition reports or inspections the landlord can join. For a landlord who's still hesitant after that pitch, a 90-day trial period under the full contract terms gives them a low-risk way to test the arrangement, with either party free to revert to a standard lease on 30 days' notice if it doesn't work out. That trial period functions as a closing tool in practice: most landlords who see consistent rent and a well-kept property during those 90 days never exercise the reversion option.
Individually owned properties and small apartment complexes are the realistic targets for this pitch. Institutional landlords and large property management companies decline this arrangement almost universally, and chasing them wastes outreach that could go toward smaller owners who are actually reachable. Social proof becomes a real asset once the first unit is running well. Bringing documented revenue reports and a reference from an existing landlord into the next negotiation is the strongest tool available for closing a second or third deal, because it replaces a theoretical pitch with a track record the next landlord can verify.
The lease structure that protects the operator as the portfolio grows
Every unit in a growing portfolio rests on the same legal foundation: a master lease paired with a sublease addendum that confirms, in writing, that short-term rental operations are permitted. A verbal understanding with the landlord is not a substitute, and treating it as one is one of the fastest ways to lose a unit mid-lease. The written addendum needs to lay out any conditions on the arrangement and specify what happens to the lease if local short-term rental laws change while the lease is active.
A handful of clauses carry outsized weight in a lease for an operator running multiple units at once. The lease needs explicit subletting permission in writing, use-of-premises language that specifically covers short-term guest stays rather than general occupancy, and clear term length and renewal conditions, since longer terms reduce how often the operator has to renegotiate. It also needs exit terms for when a unit becomes financially unviable, with clear specification of what happens if local regulations shift mid-lease. Once the first lease is proven out and running smoothly, that document becomes the template: building a master addendum that can be reused with small market-specific adjustments cuts legal costs significantly and speeds up deal flow on every unit from the second through the tenth. Actively seek out buildings that already operate as Airbnb-friendly, along with corporate lease structures that permit flexible occupancy by default, because they remove most of the negotiation phase.
Insurance sits outside the lease itself but matters just as much. Standard renters' insurance doesn't cover commercial hosting activity, and Airbnb's AirCover isn't a substitute for a dedicated short-term rental policy. A proper policy needs to be in place before the first guest ever checks in, with the landlord named directly on it, both to protect the property and to reinforce the trust that made the landlord say yes.
The operational wall between three units and ten, and the hiring sequence that gets past it
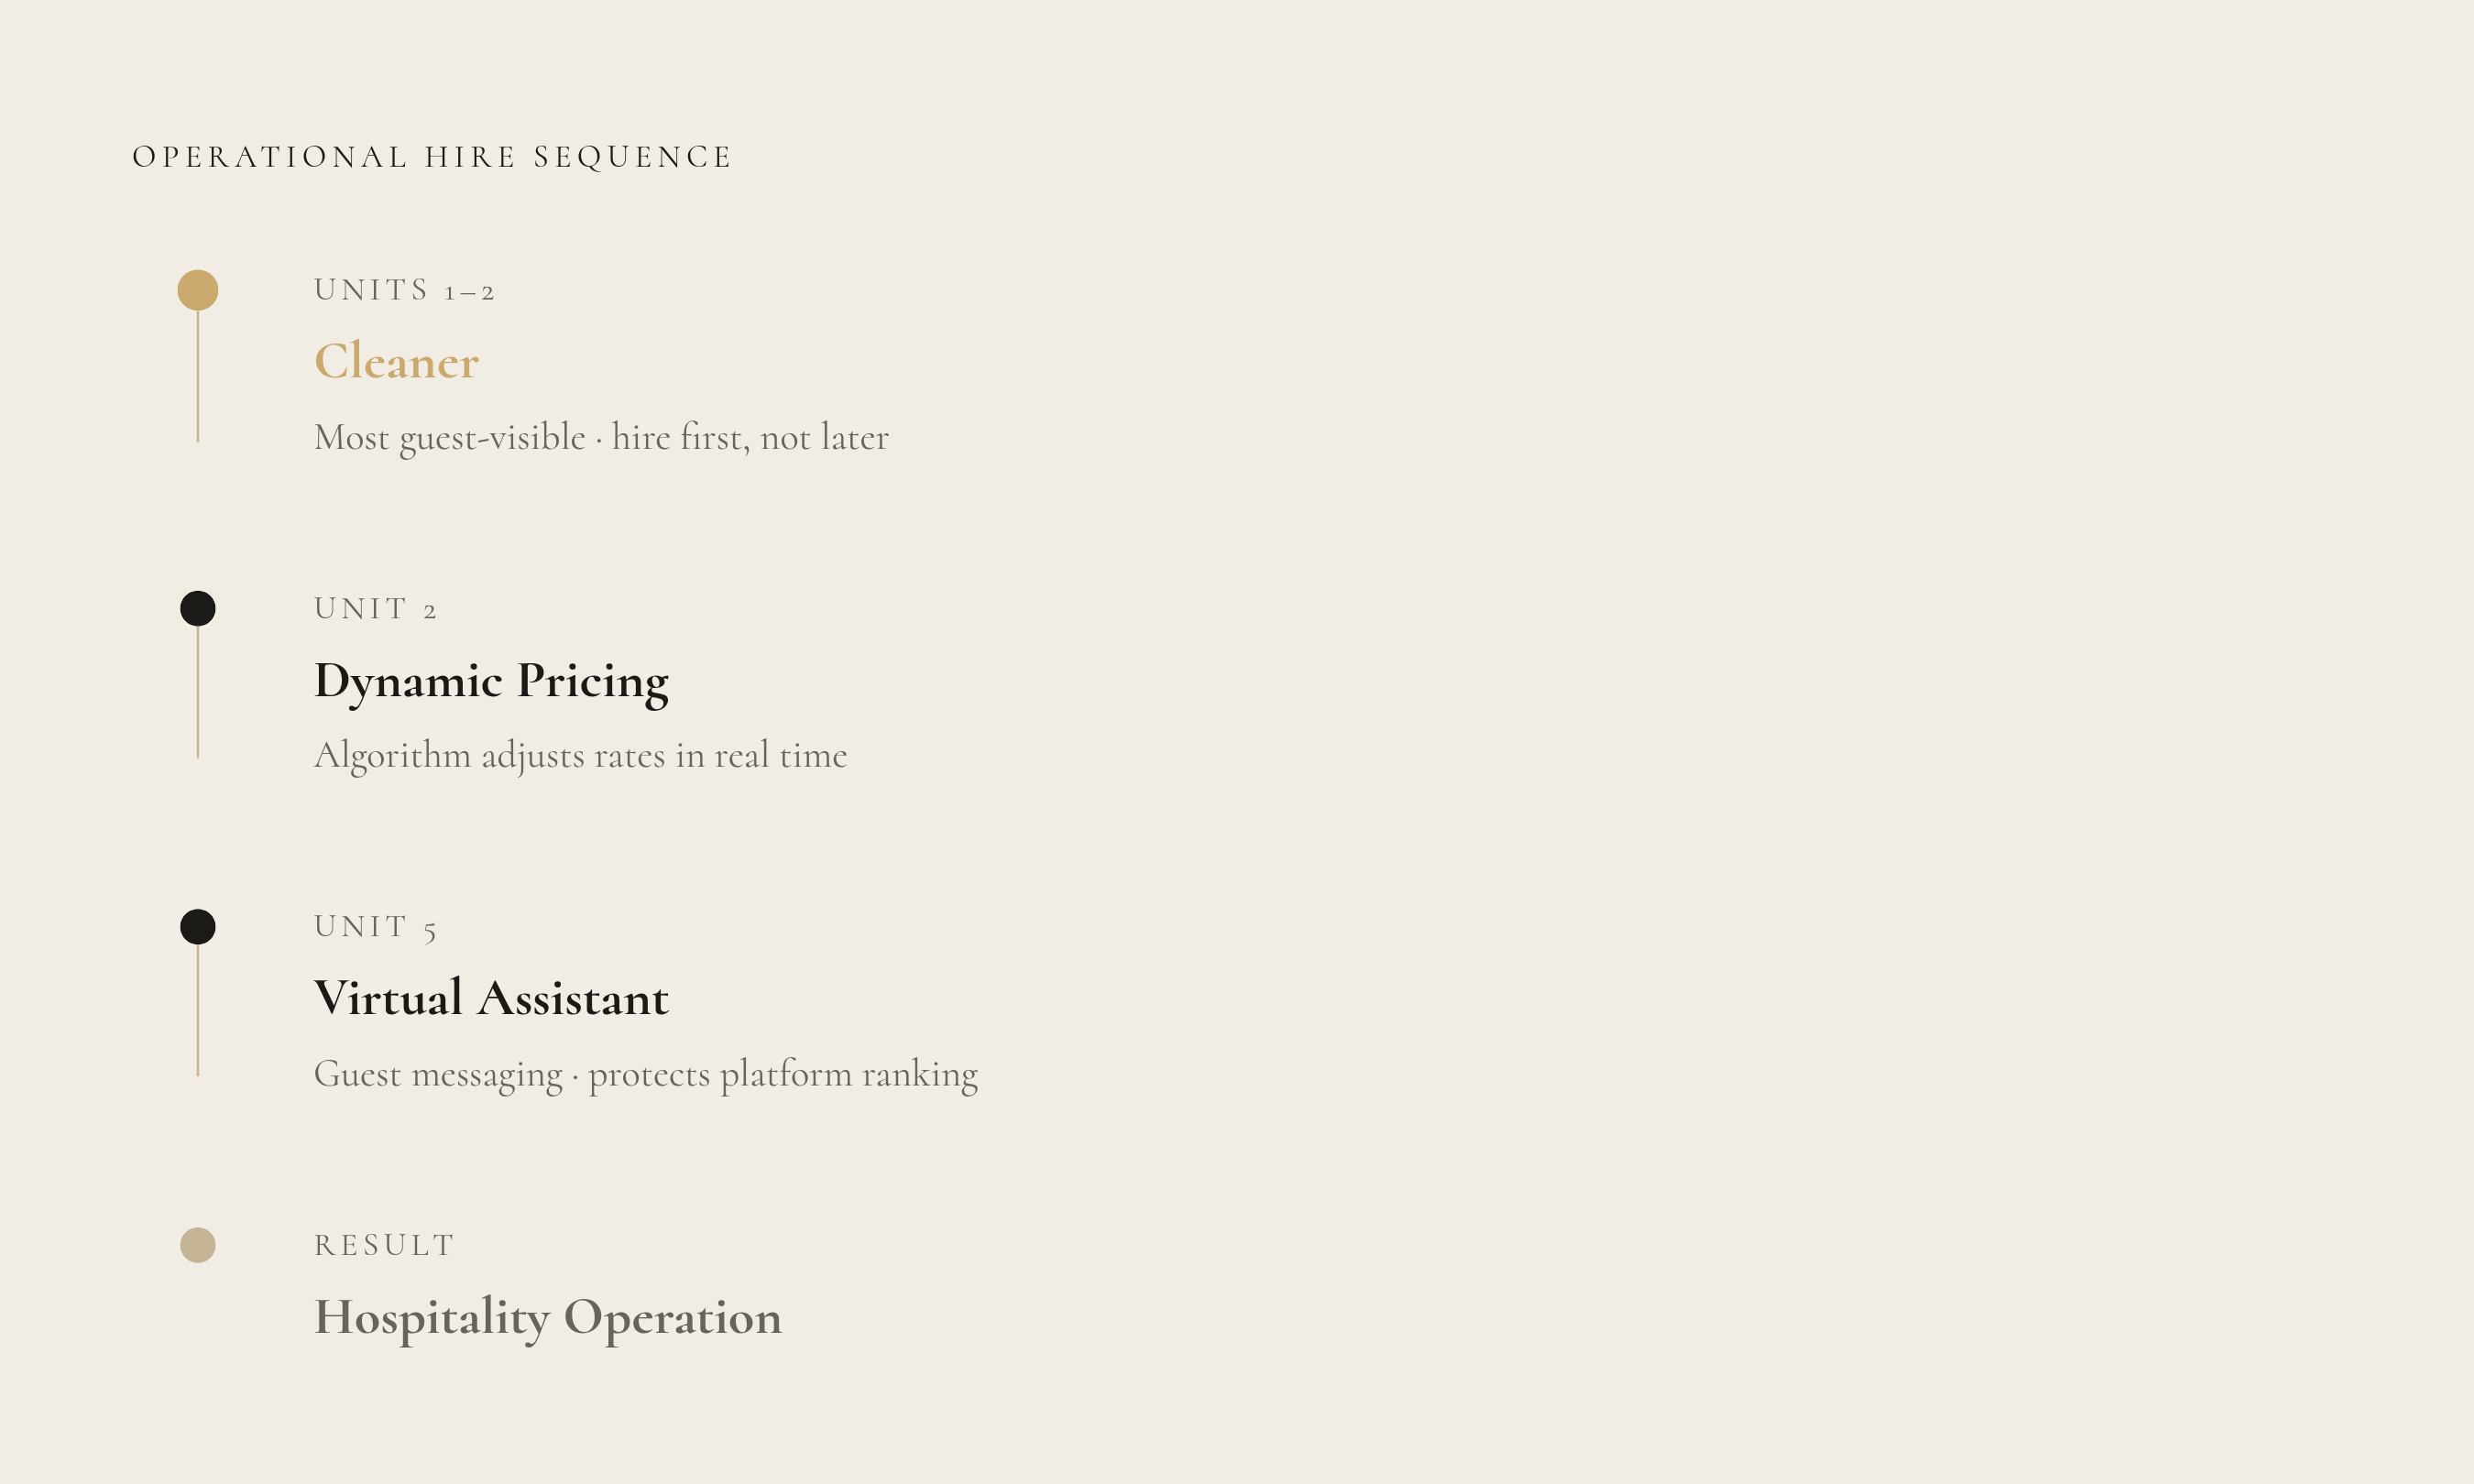
Somewhere between three units and ten, self-management stops working, no matter how organized you are. The volume of turnovers, guest messages, and pricing decisions outpaces what one person can handle without something slipping, and the units that slip first are usually the ones generating a bad review before the operator even notices a problem. To get past that wall, you need a specific hiring sequence, applied in order.
A cleaner should come on board at unit one or two, not later. Cleaning is the most time-consuming task in the operation and the most visible to guests, and a bad turnover is the fastest route to a review that drags down an otherwise solid listing. Dynamic pricing software belongs in place by unit two as well. Manual pricing simply can't keep pace with algorithm-driven tools that adjust rates in real time based on demand, seasonality, and local events, and an operator still pricing units by hand at that stage is leaving revenue on the table every night. Next, add a virtual assistant for guest messaging, around unit five. Responsive communication is required to maintain platform rankings, but once message templates are built out, it doesn't need to come from the operator personally. Brought in at the right stage, that sequence turns a growing stack of individual units into something that actually runs like a hospitality operation, not a collection of side hustles sharing one overwhelmed operator.